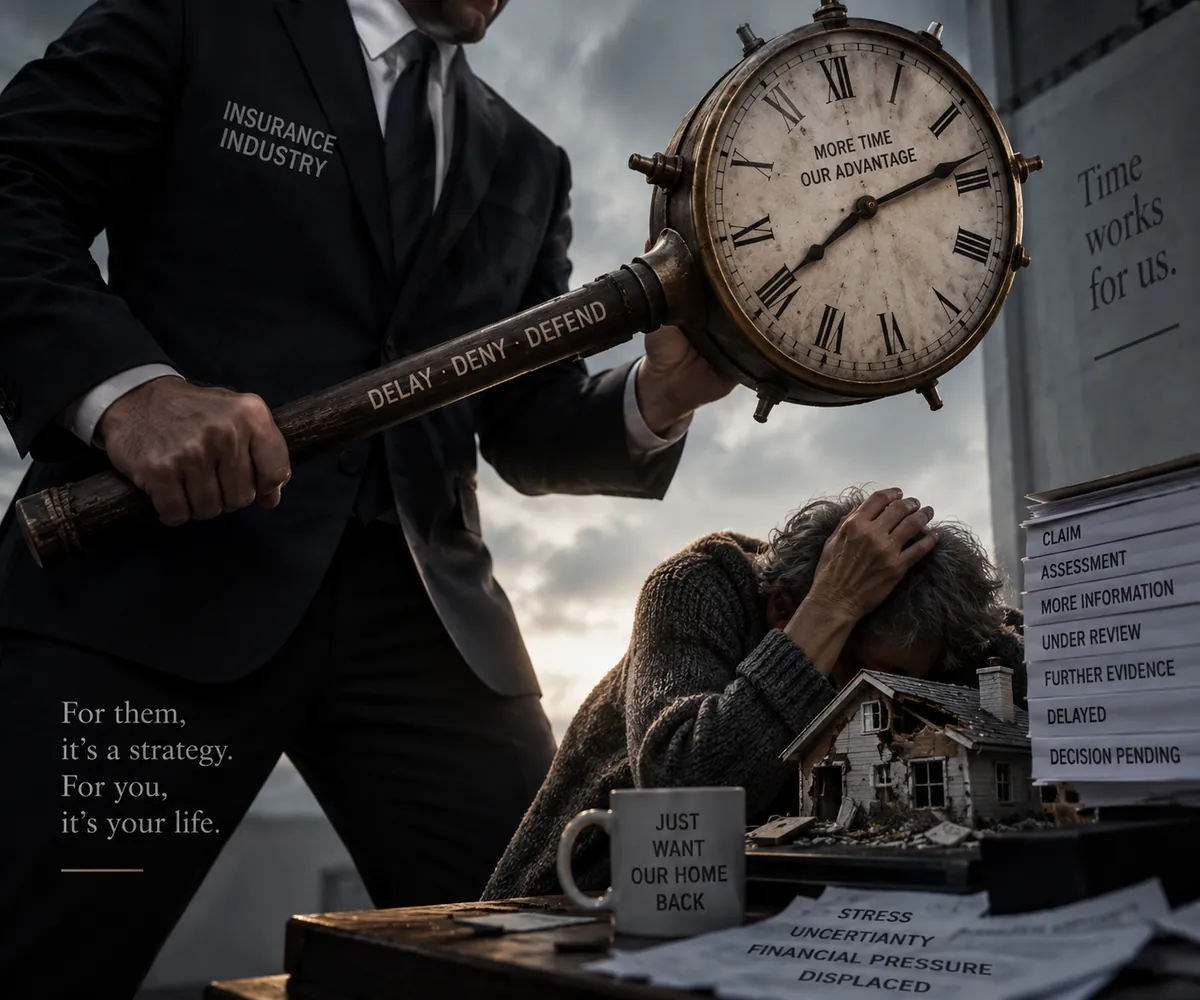
Clock as cudgel
The clock insurers signed up to, and quietly stopped watching
By Andrew Crane ·
Every big insurer in Australia has signed a Code that says a claim decision comes within four months, or twelve in extreme cases. The Code is public. So is the record of what actually happens. The evidence shows that Australian insurers are breaking their own code routinely, almost always without consequence for anyone but the policyholder.
Anchor: General Insurance Code of Practice (2020 edition, as current), paragraphs 68 to 78; House of Representatives Standing Committee on Economics, Flood failure to future fairness (October 2024); Bourova, Ramsay and Ali, Geographical Research (2022).
Background view
There is a three-word slogan long associated with the insurance industry the world over: Delay, Deny, Defend (it is the title of Jay Feinman’s 2010 book on the subject). It’s said to be the playbook of the industry, and it rings true. It works methodically from the easiest and least costly response to the hardest and most costly, and historically it’s worked for them.
The average policyholder has only one home. After a major event, if they can’t live in that home, the implications mount fast. The cost of alternative housing, the uncertainty about what the insurer might do, and still having to pay their own mortgage and keep up the premiums all put enormous pressure on the policyholder and their family. The insurer experiences none of these pressures. It knows that the longer it makes a policyholder wait, the more amenable they become to a negotiated settlement that suits it.
I was once told, when I refused a cash settlement that undervalued repairs, “OK, then we’ll just play the long game.” And they did: 874 days in total. I was caring for a dying mother and a disabled adult family member at the time, and they knew it. That was an earlier claim, not the one this site is about, and I name no insurer; the point is the method.
What the Code says, in its own words
The Insurance Council of Australia writes the Code; the insurers sign it; their product disclosure statements boast about it. Part 8 is the claims part, and it is not ambiguous:
- Within 10 business days of your claim, the insurer tells you what information it needs, appoints an assessor if it needs one, and gives you “our estimate of the likely timeframe and process” (paragraph 68).
- It updates you “at least every 20 business days” (paragraph 70).
- If it hires an external expert, it asks them to report “within 12 weeks” and tells you if they miss it (paragraph 74).
- “Our decision will be made within 4 months of receiving your claim” (paragraph 77).
- The only way out is paragraph 78: an extraordinary catastrophe, suspected fraud, a customer who will not respond, or a customer who asks for a delay. Even then the decision comes “within 12 months”.
That is the deal. Four months. Twelve if the sky falls in.
What the record says
The Hollard case decided by the Federal Court this week: claim lodged 31 October 2021, decision letter 28 April 2023. Eighteen months, and the decision was wrong ([2026] FCA 1487, paragraphs 24 and 80).
Thirty policyholders interviewed by Melbourne researchers after bushfires, floods and storms: “Only four received decisions within timeframes prescribed by the General Insurance Code of Practice.” Eleven waited six to twelve months; nine waited more than a year (Bourova, Ramsay and Ali 2022, page 542).
A parliamentary committee after the 2022 floods heard so much of this that it recommended insurers be made to report every claim still unresolved after twelve months, and to pay out automatically when they blow it (Flood failure to future fairness, Chapter 3 and Recommendations).
ASIC’s own snapshot of 218,256 home claims lodged in early 2022 found that only a small minority of severe-weather claims had received a first repair or a first cash settlement within twelve weeks (REP 768, August 2023, page 5).
Comment
Here is the thing about a four-month promise. It is not a target. It is not a KPI buried in an annual report. It is a published undertaking that every signatory makes to every customer, and the sector’s own monitor, the Code Governance Committee, exists to police it.
So when a claim runs to eighteen months, two things are true at once. The customer has been failed, and the Code has been breached. The second one has a paper trail, a committee and, since 2021, a regulator with a civil penalty in its pocket. But bloody hell, how rarely we see it enforced.
Sources
- General Insurance Code of Practice, Insurance Council of Australia, 2020 edition (current), Part 8 “Claims”, paragraphs 68, 70, 74, 77 and 78. insurancecouncil.com.au/cop.
- ASIC v Hollard Insurance Partners Limited [2026] FCA 1487, paragraphs 24, 80.
- Bourova E, Ramsay I and Ali P (2022), “The arduous work of making claims in the wake of disaster”, Geographical Research 60(4), page 542 (open access).
- ASIC Report 768, Navigating the storm, August 2023, page 5.
- House of Representatives Standing Committee on Economics, Flood failure to future fairness, October 2024.
- Financial Rights Legal Centre, factsheet “Insurance claim delay” (plain-English summary of the Code timeframes).
- Feinman J M (2010), Delay, Deny, Defend: Why Insurance Companies Don’t Pay Claims and What You Can Do About It, Portfolio.